
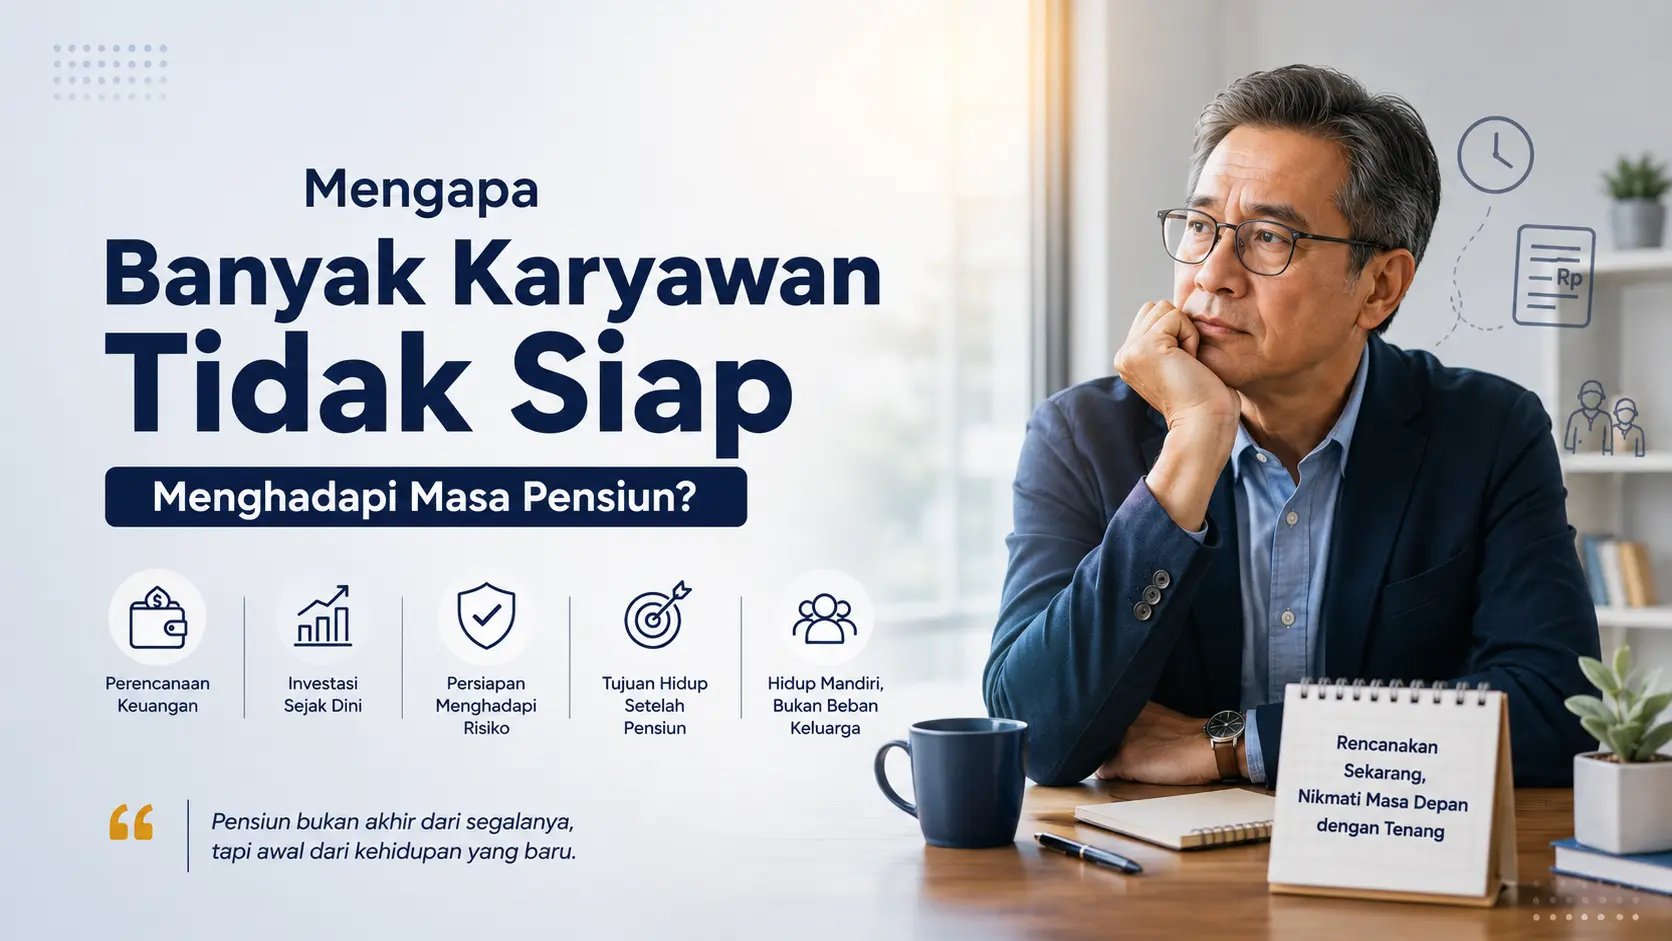
Have you ever imagined what life would be like after your last day at work? No more office routine, monthly targets, or a paycheck coming in at the end of every month.
At first, it might sound like fun. However, when that moment actually arrives, quite a few people end up feeling confused, anxious, or even lost.
In fact, the reason many employees aren’t prepared for retirement isn’t just about a lack of money. Many haven’t created a financial plan, aren’t mentally prepared, and don’t know what productive activities they can do after they stop working.
In fact, retirement can be an enjoyable phase of life if you start preparing for it during your working years—especially with your partner.
So, what are the causes? And how can you prepare to ensure that your retirement remains comfortable, independent, and prosperous? Read on for more details.
The Importance of Planning for Retirement While You’re Still in Your Working Years
1. Reducing the Financial Burden in Old Age
The sooner you start saving for retirement, the lighter your financial burden will be once you no longer have a steady income.
Funds set aside during one’s working years can be used to cover daily expenses, medical costs, and even unexpected expenses without having to rely on others.
According to Organization for Economic Co-operation and Development (OECD), Financial planning early on helps people maintain their quality of life after retirement while reducing the risk of financial hardship in old age.
2. Better Prepared to Face Various Risks in the Future
No one can predict future health conditions, inflation, or economic changes. By having a solid retirement plan in place, you’ll have a financial cushion to fall back on when facing these situations.
According to World Bank, people need to build financial resilience starting in their productive years so they are better prepared to face economic changes and increased life expectancy in the future.
3. Using Compound Interest to Build a Sufficient Retirement Fund
The earlier you start saving or investing, the greater your chances of benefiting from compound interest.
The value of your investment will continue to grow, so the retirement savings you accumulate will be much larger than if you had started just a few years before retirement.
According to Investor.gov from U.S. Securities and Exchange Commission (SEC), Starting to invest as early as possible can provide long-term benefits because your money has more time to grow.
4. Freeing Children from the Term “Sandwich Generation”
One of the key reasons for setting aside retirement savings is so that children won’t have to bear the financial burden of caring for their parents in the future.
If you’re financially independent, you can still enjoy your retirement without burdening future generations.
Put an end to the “Sandwich Generation” tradition in your family. After all, children are not financial savings for the future, but simply a trust and a blessing.
Don’t let your child feel burdened or worried:
“I have to repay my parents for everything they’ve done for me now that they’ve retired; I have to give them money every month.”
However, this actually traps them in those thoughts and expectations, preventing them from enjoying their youth and saving for the future.
5. Freedom to Choose Your Lifestyle After Retirement
Retirement doesn’t mean you have to stop enjoying life. In fact, during this phase, you have more time to pursue hobbies, travel, start a business, or spend time with your family.
All of that will be easier to achieve if you’ve laid the financial groundwork well in advance.
Don’t just sit around at home mulling things over once you retire.
Do things you enjoy with your partner, family, or friends. That sense of happiness will help you live longer.
See Also: “Why Do Many Productive Employees Choose to Quit Quietly? “
Signs That an Employee Isn't Ready to Retire
Some signs are often overlooked, even though they can have a significant impact later in life.
Do you experience any of the following symptoms?
- I don't have a retirement savings goal yet.
- Does not have any savings or long-term investments.
- All of my income goes toward monthly expenses.
- Still has a large amount of consumer debt.
- Not knowing what their living expenses will be after retirement.
- Still relying on a monthly salary.
- Has no plans for activities after retirement.
- Believing that children will be a source of income in old age.
- I have never attended a retirement preparation training session.
- Failure to understand the risks of inflation to pension funds.
Why Are So Many Employees Unprepared for Retirement?
1. Lack of Financial Planning for the Future
One of the main reasons why many employees are not prepared for retirement is the lack of a clear financial plan.
Many people focus on meeting their current needs without calculating how much money they’ll need once they stop working.
In fact, structured financial planning is the cornerstone of building financial security for retirement.
2. Always Thinking, “Ah, There’s Still Plenty of Time”
Many employees feel that retirement is still a long way off, so they put off preparing for it. In fact, time is the most valuable factor in building a retirement fund.
The longer you wait, the more you’ll have to set aside each month.
The mindset of “Ah, I’m still a long way from old age, so I might as well just enjoy the good times for now” sets you up to live without preparing for retirement.
According to Fidelity Investments, starting early yields far better results than waiting until you’re close to retirement age.
3. A Hedonistic Lifestyle: Unable to Save or Even Set Aside Money for Retirement
An increase in income is often accompanied by a more affluent lifestyle. As a result, income is spent on wants rather than needs. This habit makes it difficult for people to build savings or make long-term investments.
When you choose to buy things based on wants rather than needs, it’s actually not a good thing—it will only trap you in a life of excessive consumption.
“I’ll buy some clothes as a treat for myself—and a bag for when I go out next week, too.”
That desire, which keeps popping into your mind, can have a negative impact, because as a result, you won’t be able to save for retirement.
According to Investopedia, maintaining a balance between one’s current lifestyle and long-term financial goals is essential for building assets for the future.
4. Still Following the Tradition of “There Are Still Children; We Can Ask for Money Later”
There are still many people who view their children as a guarantee for their old age. This mindset can actually place financial pressure on children, giving rise to the “sandwich generation” phenomenon.
Will having a child ensure that your needs in old age are met? Or will it actually create new problems?
What if your child is already married?
That’s the question you need to ask yourself if you still have the mindset that “children are a guarantee for their parents” old age and must repay their parents’ kindness.”
On the contrary, it will continue to perpetuate structural poverty that will never end in your family line.
5. Reluctance to Invest Because They Consider It Too Risky and Fear Losing Money
Some people choose to simply keep their money in a savings account because they’re afraid to invest. In fact, if done in line with one’s risk profile and financial goals, investing actually helps combat inflation, thereby preserving the value of one’s retirement savings.
Don’t think, “I don’t want to invest because I’ll definitely lose money.”
There are methods and theories for everything; if you have a strong understanding of personal finance, investing is a long-term strategy for living comfortably in your later years.
So, make sure you understand the risks and investment instruments before you get started.
As explained by U.S. Securities and Exchange Commission (SEC), understanding investment risks and aligning them with your goals and financial capacity is an important step before deciding on the right investment option.
6. I Have Debt; My Salary Is Just Enough to Keep My Head Above Water
The phenomenon of ‘digging one hole to fill another’ often occurs in society because people’s salaries aren’t enough to meet their needs, so they end up taking on debt.
As a result, financial circumstances burdened by monthly payments make it difficult for people to set aside money for the future. In fact, quite a few people still have debt when they reach retirement age, which makes their financial situation even more difficult.
7. Lack of Education and Outreach by the Company
Not all companies have educational programs on retirement readiness. Yet the transition from the workforce to retirement requires financial, mental, and social preparedness, as well as planning for activities after retirement.
If your company or organization does not yet have an awareness program regarding retirement planning, you can participate in Pre-Retirement Training Program at Maximum Life Group.
This training program is designed to enhance participants’ readiness through financial education, mindset development, planning for productive activities, and lifelong learning.
With the right preparation, you’ll not only be ready to stop working, but also ready to embark on a new chapter in your life—one that’s independent and productive.
See Also: “Jakarta Retirement Training Encourages Participants to Remain Productive During Retirement“
How Can You Tell If You're Ready for Retirement?
The simplest way is to assess your current financial situation and life plans.
Ask yourself:
“Do I already have sufficient retirement savings, long-term investments, health insurance, plans for what to do after retirement, and sources of income other than my salary?”
If most of your answers are still “not yet,” then this is the best time to start preparing.
The sooner you conduct an assessment, the better your chances of improving your situation before reaching retirement age.
The Consequences of Not Setting Aside Retirement Savings Early On
Failing to plan for retirement can lead to a variety of consequences, ranging from difficulty meeting basic living expenses, having to rely on children or family members, a decline in quality of life, to increased psychological stress due to financial uncertainty.
In addition, rising inflation causes the value of money to decline steadily, so savings that aren’t properly managed will run out even faster.
Therefore, preparing for retirement is no longer an option, but a necessity that must begin during one’s working years.
Prepare for Retirement by Taking a Retirement Planning Course with Maximum Life Group!
Retirement is not the end of one’s career, but rather the beginning of a new chapter in life. To ensure this phase is peaceful, productive, and financially secure, thorough preparation is essential—both financially and mentally—as well as planning for activities after retirement.
Maximum Life Group We are a company dedicated to human resource development through educational programs, training, mindset development, and lifelong learning.
Through the training program Pre-Retirement Preparation Period, Maximum Life Group can help you prepare for retirement early on—starting during your working years.
With the support of a professional coach who has over 16 years of experience, you’ll be equipped with the skills you need in areas ranging from human resources (HR) and leadership to financial management, mental well-being, and the best ways to enjoy your retirement.
Don’t wait until you reach retirement age—enroll in the Pre-Retirement Preparation Training program today with Maximum Life Group!
Click the banner below to connect with us!